What a Workers’ Compensation Commutation Actually Means for Your Benefits
No. Not without finding out exactly what you would be giving up first. A fast settlement offer after a Delaware work injury almost always favors the insurance company’s timeline, not yours, and once you sign a commutation agreement, you cannot go back and ask for more if your injury turns out worse than expected.
That does not mean every offer is bad. Some are fair, and some injured workers genuinely benefit from settling early, especially once treatment has stabilized and the value of the claim is easier to see clearly. The problem is telling the difference before you sign, not after.
Why the Insurance Company Calls So Soon After Your Injury
Insurance carriers track the total cost of an open workers’ compensation claim for as long as it stays open. Every additional month of wage benefits, every new round of physical therapy, and every future surgery adds to that number on their books. A closed file costs the insurer nothing more, which is exactly why adjusters often raise the idea of a settlement while you are still in the middle of treatment, before anyone knows the full extent of your injury or whether you will need further care.
An early offer is a business decision on their end, made with the benefit of claims data most injured workers never see. It should be treated as a starting point for negotiation on yours, not a deadline to meet. The fact that an adjuster called quickly does not mean the number they led with reflects what the claim is actually worth.
What “Commutation” Means Under Delaware Law
Delaware does not call this a simple buyout. The legal term is commutation, and it is governed by 19 Del. C. § 2358. Under that statute, either side can ask the Industrial Accident Board to convert your future workers’ compensation payments into a single present-value payment, discounted at 5% interest with annual rests. The Board has to approve the deal before it becomes final. Nobody, including your employer’s insurance carrier, can commute your claim on a handshake or an email exchange.
The Board also has to look at what you will actually walk away with. Under the statute, it will not approve a commutation without reviewing the attorney’s fees and costs coming out of your settlement, and it evaluates the deal based on your net recovery after those amounts are subtracted, not the headline number in the offer letter. A settlement that sounds generous on paper can look very different once fees, liens, and outstanding medical bills come out of it.
Commutation Is Not the Only Way to Resolve a Claim
Not every resolution has to be a full commutation. Delaware also allows agreements on compensation that keep weekly benefits running under an approved schedule, without closing out your right to future medical treatment the way a commutation does. Knowing the difference matters, because an adjuster describing an offer as a “settlement” does not always mean they are proposing to end your medical coverage permanently. Ask directly whether the proposal is a full commutation under Section 2358 or a more limited agreement, and get the answer in writing before you respond. The difference changes everything about how much leverage you keep if your condition changes later, and it is a fair question to ask an adjuster directly rather than assume based on how the offer was worded over the phone.
What You Give Up When You Commute Your Claim
A commutation does not just end your wage checks. It closes out your entire workers’ compensation case, which includes benefits many injured workers do not think about until they need them months or years down the road.
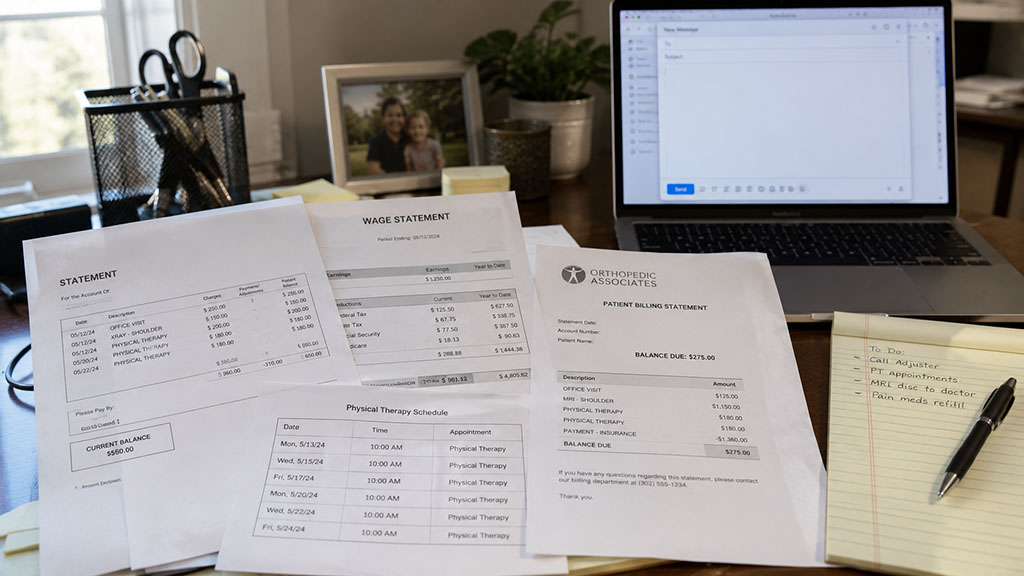
- Ongoing medical treatment. Once you commute, workers’ comp no longer pays for future doctor visits, physical therapy, injections, or surgery connected to your injury, even years later, no matter how directly it traces back to the original accident.
- Wage replacement benefits. Any future checks for total or partial disability stop, regardless of whether your ability to work changes for the worse after you sign.
- Mileage reimbursement. You lose the right to be reimbursed for travel to medical appointments related to the injury, which can add up quickly if specialists are not local.
- Permanent impairment and disfigurement benefits. If a rating for permanent impairment has not been finalized yet, settling early can mean giving it up before anyone knows its true value.
- Death benefits tied to the claim. Some settlements can affect what a spouse or dependent would be entitled to if the injury ever contributed to your death, a piece of the negotiation most people never think to raise on their own.
Once the Board approves the commutation, this list does not come back. There is no reopening the claim because a surgery you thought you would not need turns out to be necessary two years later, and there is no second bite at a higher wage-loss number once the file is closed.
How Future Medical Costs Get Factored Into a Fair Number
The hardest part of valuing a settlement is putting a number on care you have not received yet. If your treating physician has floated the possibility of surgery, injections, or long-term physical therapy, that projected cost belongs in the settlement conversation even though it has not been billed yet. Adjusters do not volunteer this math on their own, and an offer built only around bills already paid tends to undervalue a claim where the real cost is still ahead of you.
This is also where a permanent impairment rating matters most. A rating performed too early, before swelling has gone down or before a joint has finished healing, can understate how much lasting impact the injury actually has. Waiting for an accurate rating, even if it delays a settlement by a few weeks, usually protects the value of the claim rather than putting it at risk.
How the Industrial Accident Board Decides Whether to Approve It
The Board is not a rubber stamp. Under Section 2358, a commutation can be approved when it serves the injured worker’s best interest, avoids undue hardship for either side, or applies to specific circumstances like an employee moving out of the country or an employer selling off the business. It is not supposed to be approved just because the insurance company wants to close its file faster.
The law also blocks a specific misuse of commutations: settling a claim to pay off a debt from before the injury, other than a mortgage on the worker’s own home or household furniture. If someone suggests a quick settlement to cover a hospital bill or an old loan unrelated to the injury, that reasoning does not hold up under the statute the Board is supposed to apply, and it is worth flagging to the Board directly if it comes up.
Questions Worth Answering Before You Sign Anything
A settlement number by itself does not tell you much. Before agreeing to anything, get clear answers to these questions.
- Has your treating doctor said you have reached maximum medical improvement? Settling before your condition has stabilized means guessing at a value nobody can confirm yet.
- Is surgery still on the table? A future procedure can cost far more than what an early offer accounts for, and recovery time from surgery affects future wage-loss value too.
- What is your permanent impairment rating, and has it been finalized? An unrated injury is often worth more than the number an adjuster leads with before that rating exists.
- Are you still receiving wage benefits, and would settling end them immediately? Know exactly when the money stops relative to when it would have stopped on its own under the claim’s normal timeline.
- Does the offer account for your net recovery after fees and costs? The number on the letter and the number in your bank account are not the same thing.
- What happens to any outstanding medical liens? A settlement that does not resolve liens correctly can leave you owing money out of your own recovery later.
If you cannot answer most of these with confidence, that is a sign to slow down, not sign.
You Do Not Have to Decide Today
Adjusters sometimes create a sense of urgency that does not match the legal reality. Delaware gives injured workers two years from the date of the accident to reach an agreement on compensation or file an appeal with the Board, and where payments are already being made under an approved agreement, that period extends further from the date of the last payment. A pending offer from an insurance adjuster is not a countdown clock tied to that deadline, and taking time to get your treatment records, wage history, and impairment rating in order before you respond usually strengthens your position rather than weakening it.
Waiting also lets your medical picture become clearer. A rushed settlement locks in a number based on incomplete information, while a claim given time to develop gives everyone, including the Board, a more accurate picture of what fair compensation looks like.
What a Delaware Workers’ Comp Attorney Can Negotiate Beyond the Obvious
A fair evaluation of a settlement offer goes past the wage and medical numbers on the page. An attorney familiar with Delaware workers’ compensation claims can factor in the value of unresolved medical treatment, push back on a permanent impairment rating that undervalues your injury, and raise pieces of the claim that rarely show up in an initial offer, like what happens to survivor benefits if the injury later contributes to your death, or how outstanding health insurance liens get resolved as part of the deal.
The Law Office of Heather A. Long handles these negotiations on a contingency fee basis, meaning you pay nothing upfront and the fee comes out of what gets recovered, not out of your pocket before a consultation. That also means the firm has the same incentive you do: getting the highest number the facts support, not the fastest signature on the page.
FAQs about Workers’ Comp Settlements in Delaware
Can I negotiate a workers’ comp settlement offer, or is it final?
Initial offers are a starting point, not a final number. Insurance adjusters expect some back and forth, and the Industrial Accident Board still has to approve whatever amount both sides land on before it becomes binding.
What happens to my health insurance if I settle my workers’ comp claim?
Settling closes out the workers’ compensation side of your medical coverage for that injury. Any future treatment related to it would need to go through your own health insurance or another source, which is one more reason to know whether more treatment is likely before you settle.
Do I need a lawyer to settle a workers’ comp claim in Delaware?
The law does not require one, but the Industrial Accident Board still has to review the deal, and an unrepresented worker often has no way to know whether the number reflects the true value of the claim, including future medical care and any unresolved impairment rating.
Can the insurance company force me to settle?
No. A commutation requires your agreement and the Board’s approval. Refusing an offer does not cut off your existing benefits on its own, though refusing a reasonable medical exam or treatment request can affect your claim separately.
What if I already accepted a settlement and think it was unfair?
Once the Board approves a commutation, reopening the case is extremely difficult. If you have already signed something and have concerns, talk to an attorney as soon as possible to find out what options, if any, remain available to you.
Does settling affect my Social Security Disability benefits?
It can, depending on how the settlement is structured and worded. Coordination between workers’ compensation and Social Security Disability is its own area of law, and it is worth raising with your attorney before you finalize any settlement amount.
How long does it take the Board to approve a commutation once both sides agree?
Timing varies by case load and whether the Board has questions about the proposed terms. Cases with clear medical documentation and a well-supported net recovery calculation tend to move through review faster than ones missing that information.
Will settling my claim affect my ability to work for the same employer?
A workers’ compensation settlement resolves the benefits side of your claim. It does not automatically end your employment, and it does not give your employer a separate right to fire you simply because you settled a claim connected to your injury.
Talk to a Delaware Workers’ Comp Attorney Before You Sign
An offer that looks fair in an adjuster’s letter can look very different once someone reviews your medical records, wage history, and impairment rating side by side. The Law Office of Heather A. Long reviews Delaware workers’ compensation settlement offers before you sign, on a free consultation basis, with no fee unless there is a recovery. Call 302-466-5664 or visit the firm at 501 Main Street, Suite 638, Odessa, DE 19730 to find out what your claim is actually worth before you close it out for good. Bring whatever paperwork you have, including the settlement offer itself, recent medical records, and any impairment rating you have received, so the review reflects your actual claim rather than general assumptions about a typical case.